Institutional Insights: Nomura 'POST-MIDTERM CLEARING'
NOMURA CROSS-ASSET STRATEGY BRIEFING: "USE YOUR WORDS" — POST-MIDTERM CLEARING & RATES COMPLEXITY
THE TAKE: STANDARD VOL MONETIZATION MEETS "NARRATIVE MODERATION"
The cross-asset rally across equities and bonds alongside the US Dollar selloff reflects classic post-event microstructure mechanics: systematic and discretionary monetization of downside tail hedges (selling puts, unwinding VIX calls) following the initial "Blue Tsunami" knee-jerk overnight flush. Over the last decade, institutional windows to monetize equity downside and volatility spikes have compressed into tight tactical windows; with the macro world intact on Wednesday morning, accounts aggressively bought back index delta, favoring constructive, defined-risk call spread structures into year-end seasonality.
Beyond the mechanical short squeeze and post-degrossing purge, the post-election "glass half-full" narrative rests on a broader "Narrative Moderation":
Forced Capex Moderation: The Democratic sweep across Congress and key governorships is perceived as forcing a controlled deceleration on the US data-center buildout. This cools the hyperscaler "prisoner's dilemma" capex race-to-infinity, reducing equity/debt financing needs, slowing the FCF cash burn trajectory, mitigating sovereign bond crowding-out risk, and dialing back upward pressure on the US neutral rate ($R^*$).
Big Tech Pre-Emptive Alignment: Major hyperscalers (Microsoft, Amazon, Meta, Alphabet) pre-emptively mitigated regulatory tail risk by partnering with leading environmental groups (Sierra Club, LCV, NRDC) to form the "Responsible Data Center Development Collaborative." Under a Democratic legislative regime, this framework facilitates ongoing approvals—just at a measured pace—eliminating the severe left-tail fear of an outright national data-center moratorium.
Geopolitical De-Escalation & Lower Oil: President Trump's statements confirming no immediate plans for strikes against Iran post-midterms accelerated the crude liquidation ($WTI$ breaking sub-$90/bbl). Lower energy input costs pull Treasury yields and the US Dollar lower, mechanically easing US Financial Conditions (FCI) and pushing back against recent economic stagflation/left-tail recession fears.
Pushback on Wealth Taxes: Moderation of "hard-left" socialist/fiscal redistribution risks emerged as California voters blocked the high-profile wealth tax initiative, alongside broad nationwide rejection of local property tax hikes, signaling the vote was a referendum on the administration rather than an embrace of radical tax policy.
GOLD & GEOPOLITICAL FLOW SIGNAL
Gold's +3.4% rally to ~$4,064/oz delivers two specific structural messages:
Perpetual Fiscal Deficits: Reaffirms that structural fiscal deficits and elevated US government debt issuance will persist under a divided/Democratic-controlled Congress, showing no market appetite for severe fiscal austerity or deep government-spending cuts.
Middle East Flow Relief: Lower risk of imminent combat operations against Iran relieves speculated selling pressure and liquidity-raising programs from GCC sovereign wealth funds and Iranian entities.
RATES OUTLOOK: "UPPERS AND DOWNERS SIMULTANEOUSLY" (A TWO-WAY CHOP)
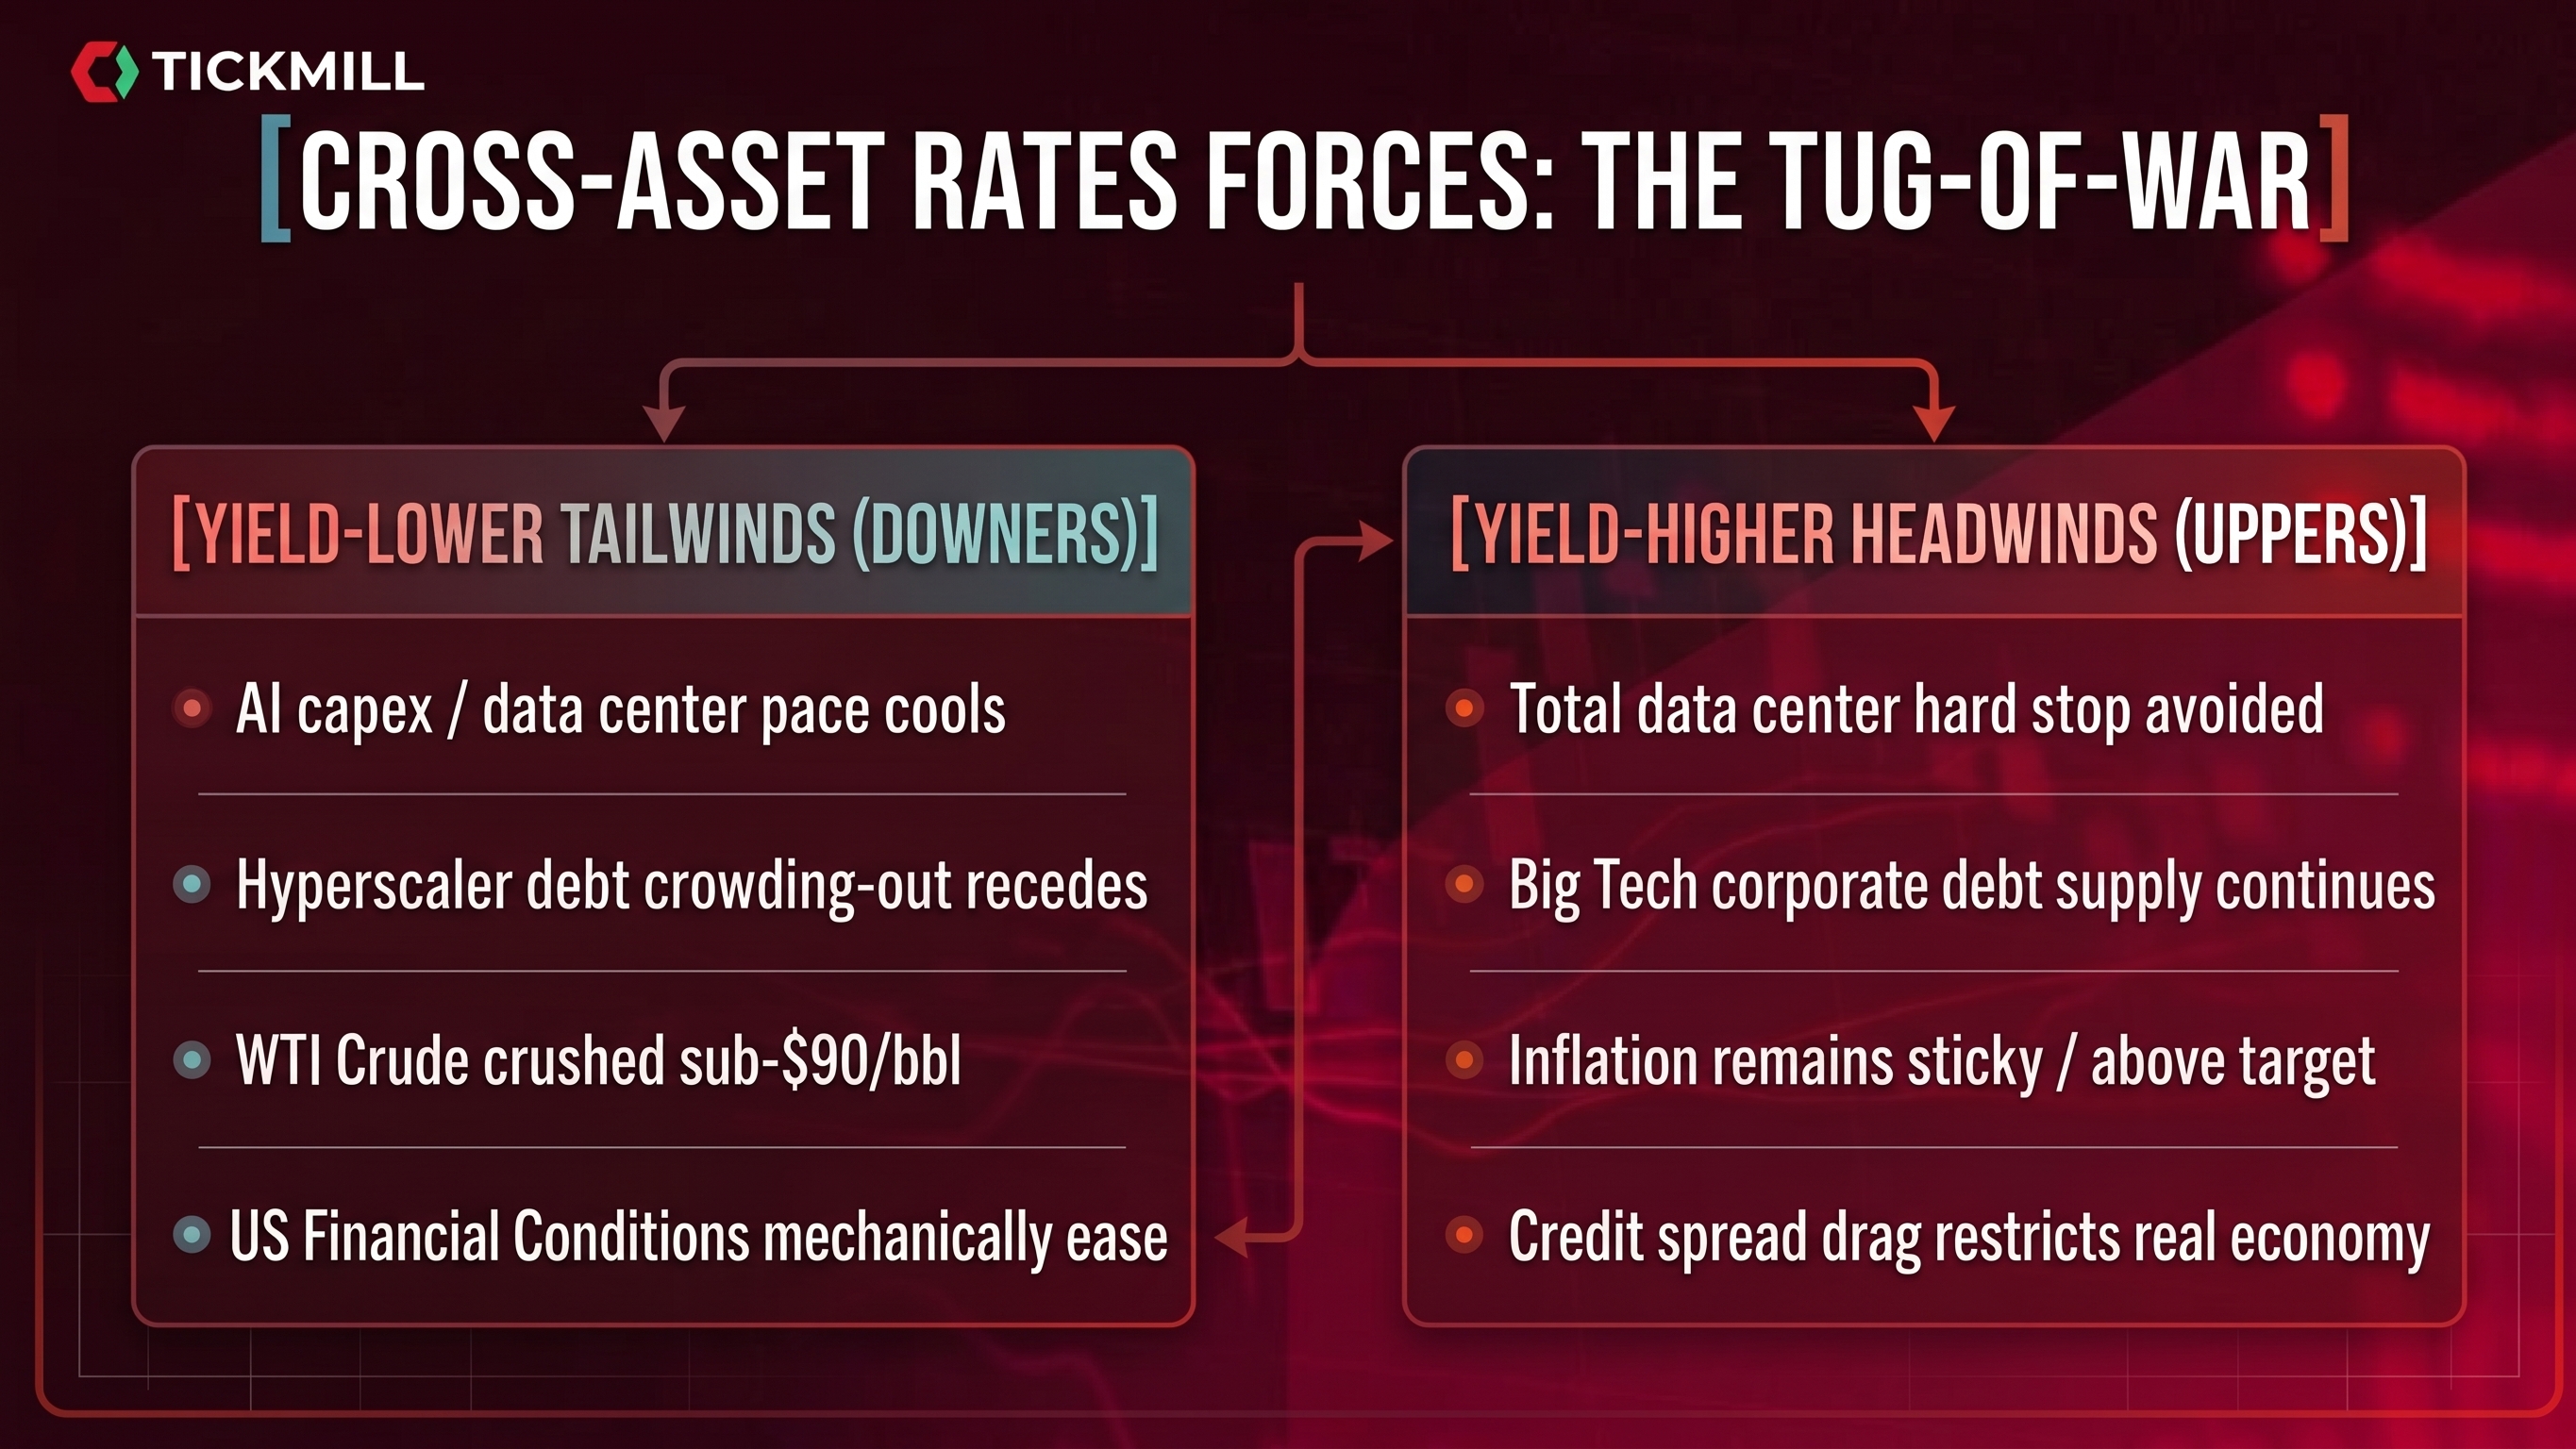
While lower oil, reduced capex crowding-out, and regulatory slowing of AI demand create an incremental tailwind for lower benchmark yields, McElligott warns against declaring a structural bull-market regime shift for US duration:
The AI Capex Dampener vs. Growth Floor: Cooling AI capex expectations trims peak GDP exuberance, but avoiding an outright data-center halt prevents a sharp economic growth scare.
Persistent Supply Drag: Mega-cap debt issuance remains robust to fund existing cluster commitments (e.g., Meta issuing a multi-tranche EUR debt package today), while elevated credit spreads and wide financing costs act as a persistent drag.
Core Rates Verdict: Treasury yields face an opaque, highly volatile two-way tug-of-war. Expect 10-Year yields to chop within a range rather than staging a one-way bull flattening, despite the near-term downward drift below 4.90%.
TACTICAL DERIVATIVES & IMPLEMENTATION PLAYBOOK
Monetize the Event Crush via Vertical Call Spreads: Avoid paying bloated single-leg delta; continue utilizing disciplined structures like SPY Nov/Dec Call Spreads (or SPX/NDX equivalents) to ride the post-midterm clearing path toward the 82% corporate buyback open window.
Fade Extreme Tail Hedges: With over 530k VIX calls monetized within the first hour of trading and VVIX dropping 17–18 points, tail hedges should be converted into defined-risk collars or harvested into spot bounces.
Equity Expression Bias: Favor balance-sheet-rich compute owners (hyperscalers) over levered infrastructure builders (neoclouds, capital-intensive power suppliers, and semicap equipment facing local regulatory scrutiny).
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!